

You might get two mid-week commentaries this week, you lucky thing, as I need to write about bitcoin. B-Day™ is approaching.
I’ll also be putting out the next in my New Orleans series, and I have some marketing to send out as well about my new quarterly reports, so lots to look out for.
But today we are looking at the next great rotation.
As you know, I’m a Charlie Morris fan and I’ve been reading a lot of his stuff this week. Charlie, if you don’t know him, used to run a multi-billion dollar fund for HSBC and is now chief investment officer at ByteTree.
Over the past couple of weeks he has put out several charts that, taken together, tell a valuable story, and perhaps one that not many have caught up with.
So, with full credit to Charlie, here it is.
The Great Rotation has begun
In March 2000 money started to abandon tech for low-volatility, defensive stocks (drinks, utilities, supermarkets). They rallied and the high-beta stocks rolled over. Overlay today’s market on the dot-com era, and high-beta stocks have followed almost exactly the same path as they did 26 years ago. Defensives have turned up on cue.
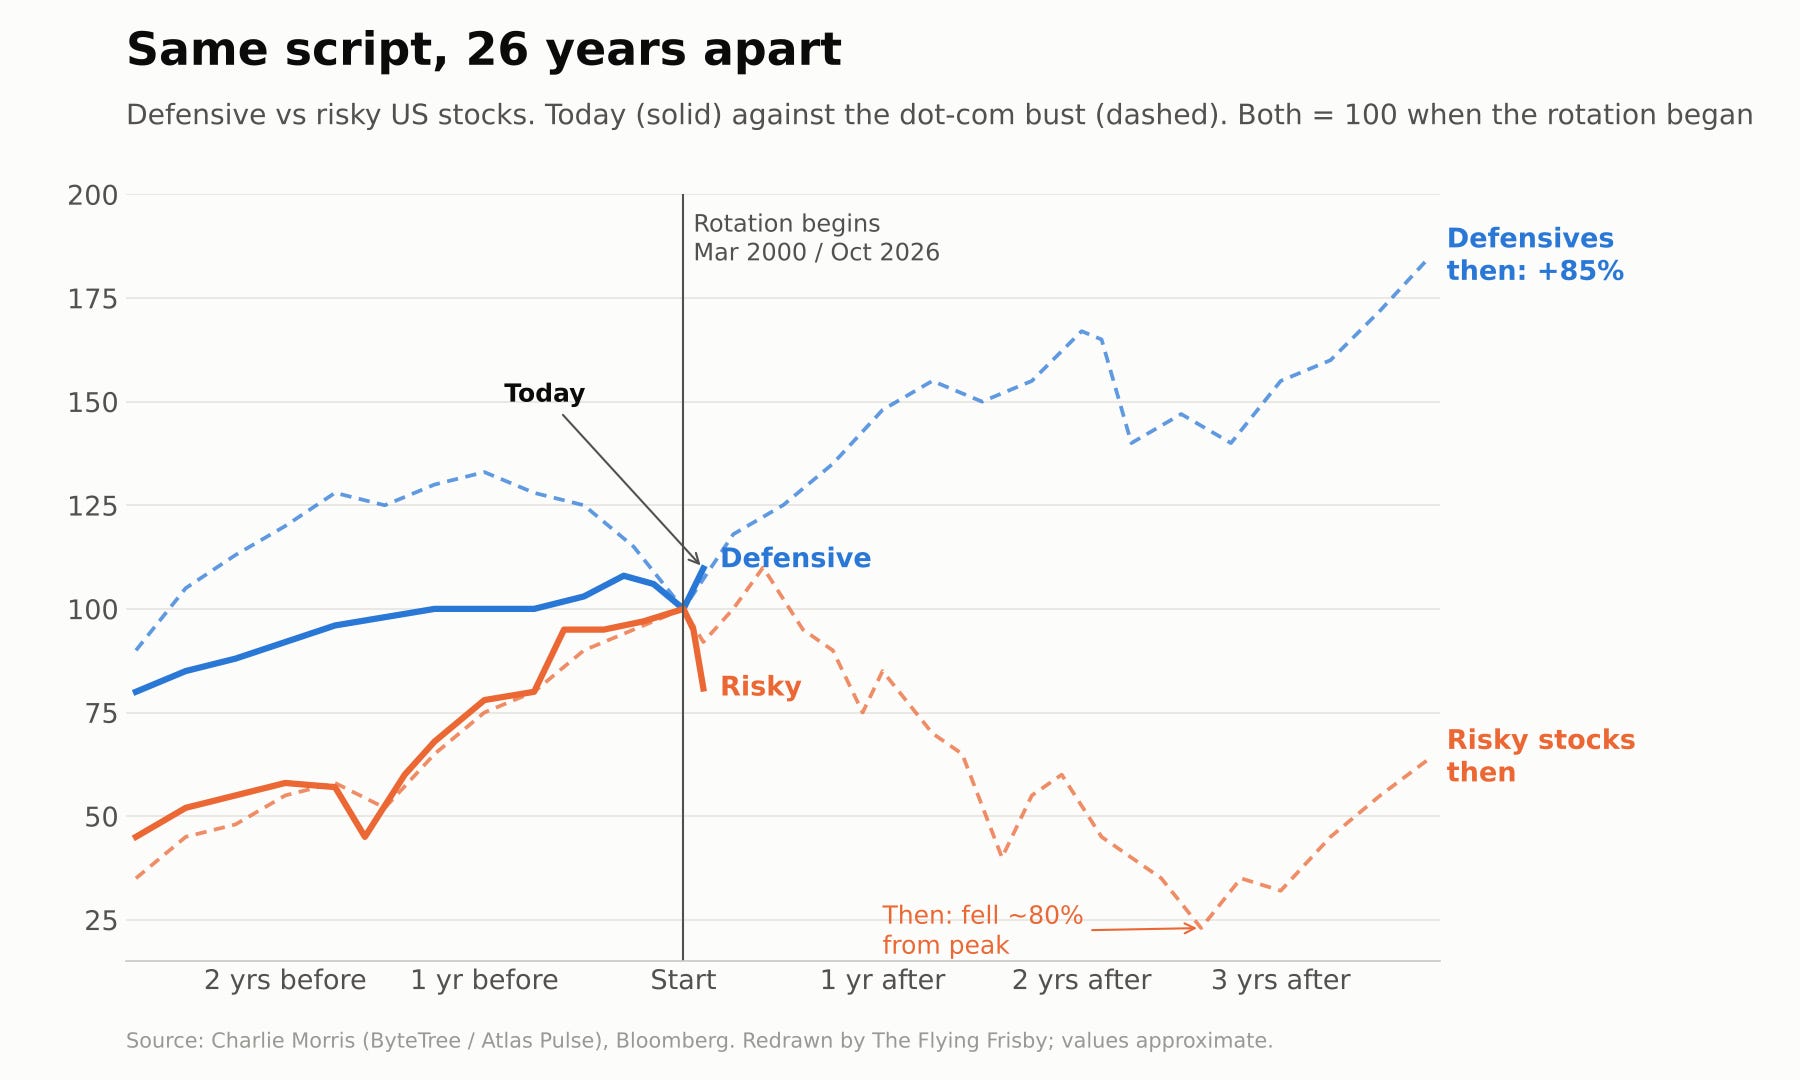
What happened next? Tech fell by 80%. It took the Nasdaq 15 years to get back to its 2000 high, though once it got going after the financial crisis, by golly did it go. Defensives did fine after 2000. They nearly doubled over the following four years.
One example today might be Coca-Cola. Boring, maybe, but it is beating the market again.
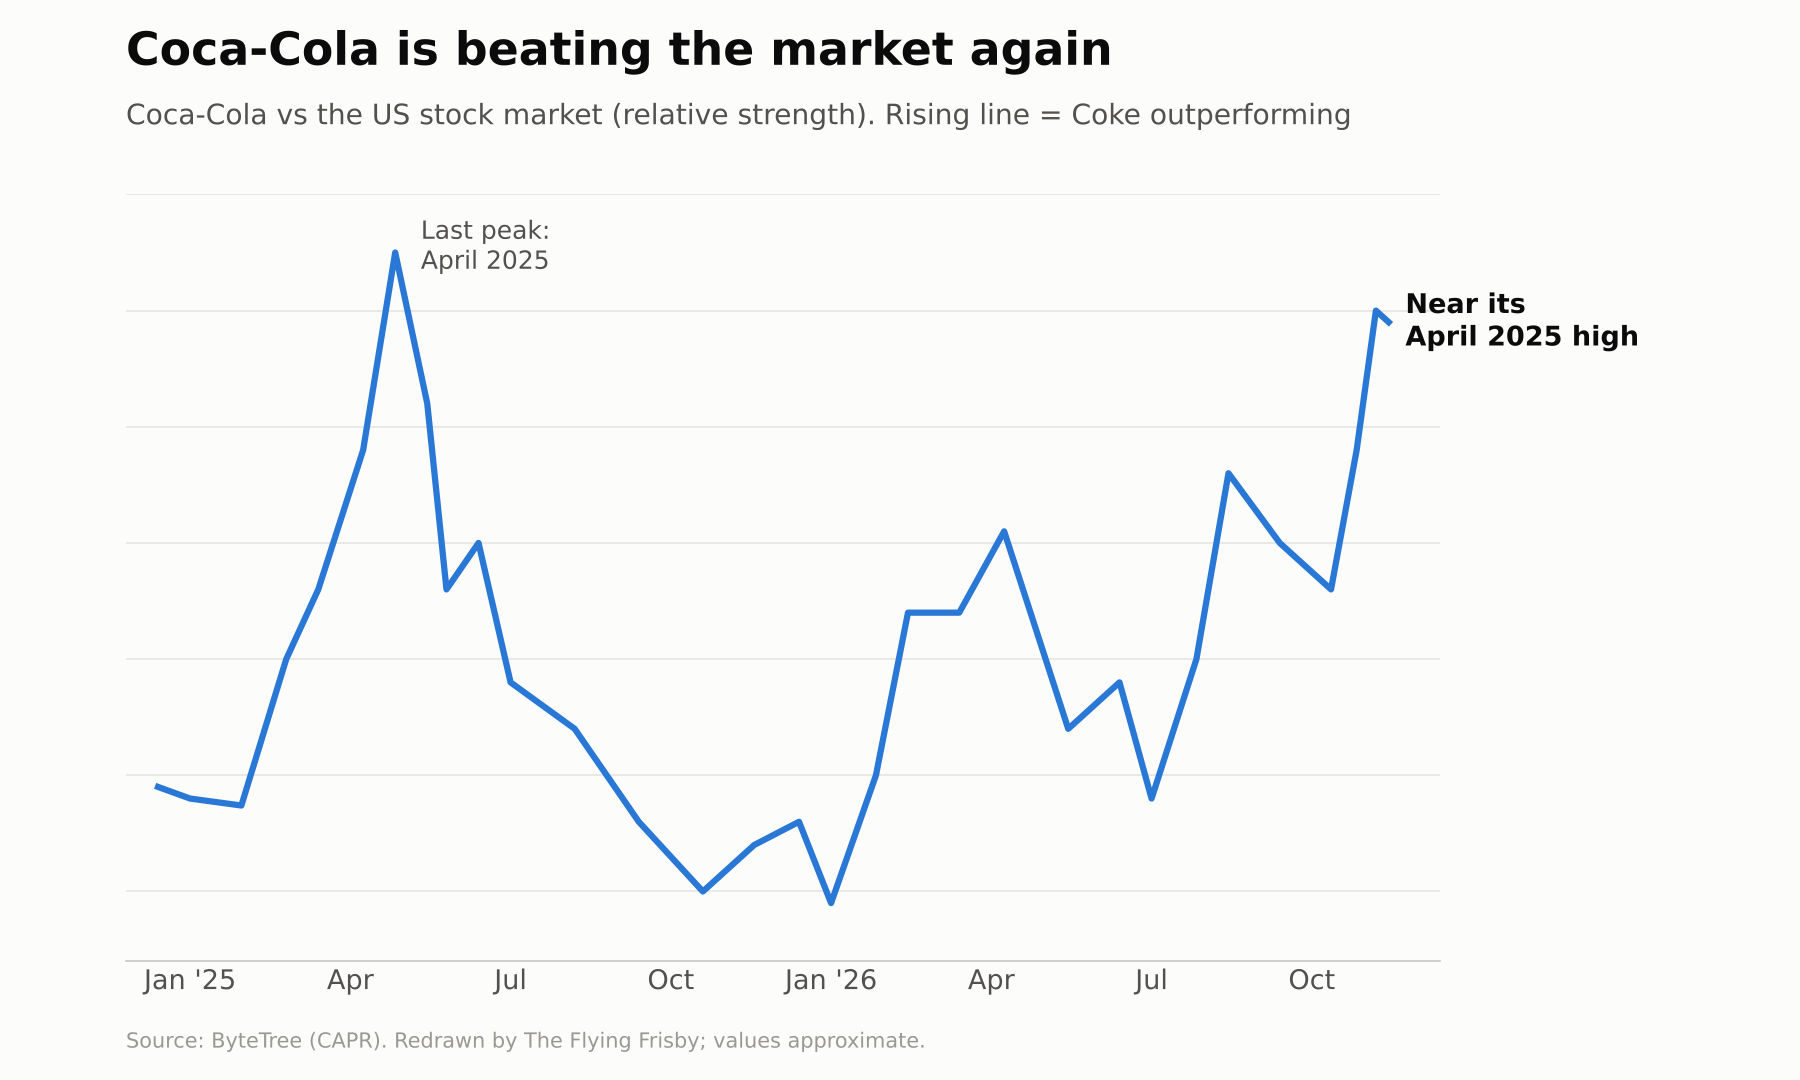
Such analogues and fractal patterns are not prophecies. History may rhyme, it may even repeat, but it doesn’t photocopy. Still, when the rhyme is this close, it bears some heeding.
Hedge funds are heading for the exits
It’s not just tech. Hedge funds are dumping commodities at the fastest pace since Russia invaded Ukraine. 2022 was a bad time to be in commodities. I know. I was in them.
In September speculators’ net long positions amounted to 14% of open interest in the Bloomberg Commodity Index, the highest since June 2022. Two months on, it has fallen to around 5%.
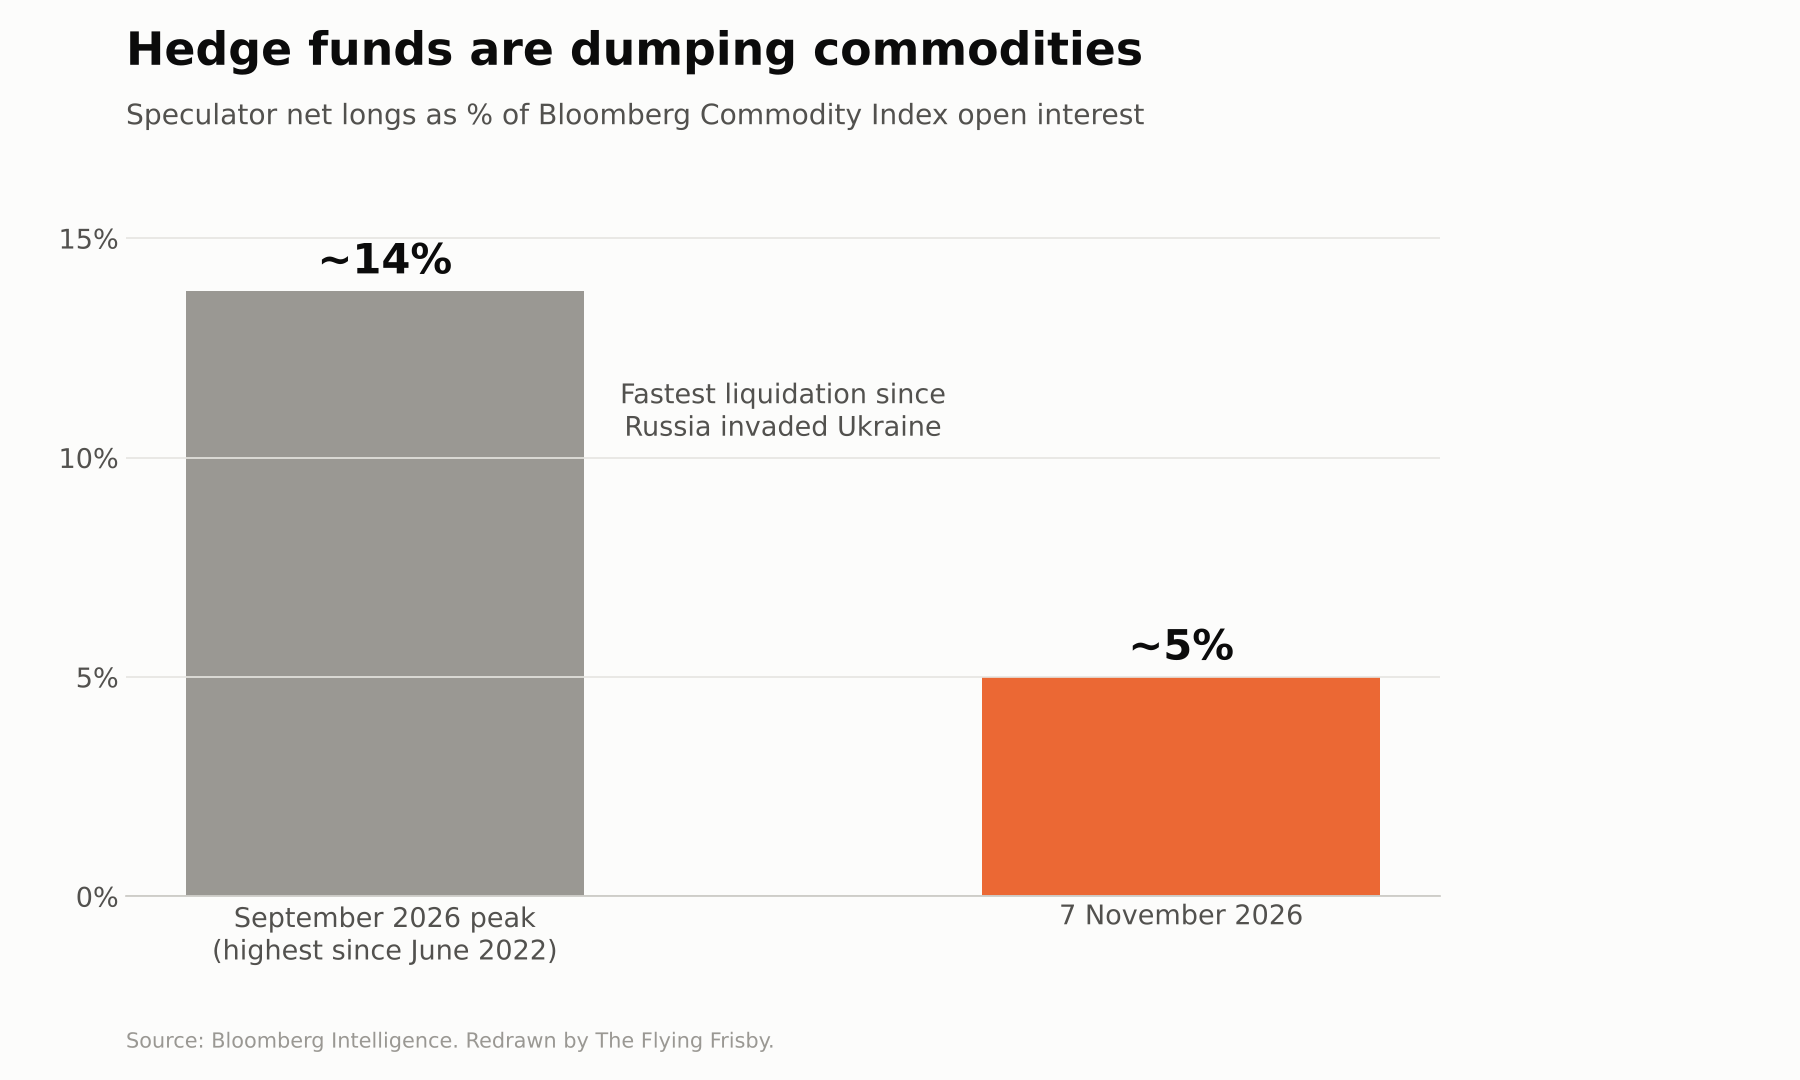
When the fast money leaves this quickly, prices feel it.
This does not bode well for commodities: oil, copper and other metals, grains and so on. Copper itself, despite so many bullish fundamentals, has now rolled over. This concerns me for obvious reasons, and it goes against everything, for example, Jeff Phillips was saying in our recent interview. That is the nature of markets. Not everyone agrees.
AI bubble deflating, commodities sold, money hiding in Coca-Cola, bonds having something of a rally. It’s all quite deflationary. Which brings me to the bit that doesn’t quite fit.
What, no inflation?
This, for me, is the humdinger. Actual US CPI inflation is 3.7%. Inflation expectation, what the market expects inflation to average over the next five years, is 2.4%.
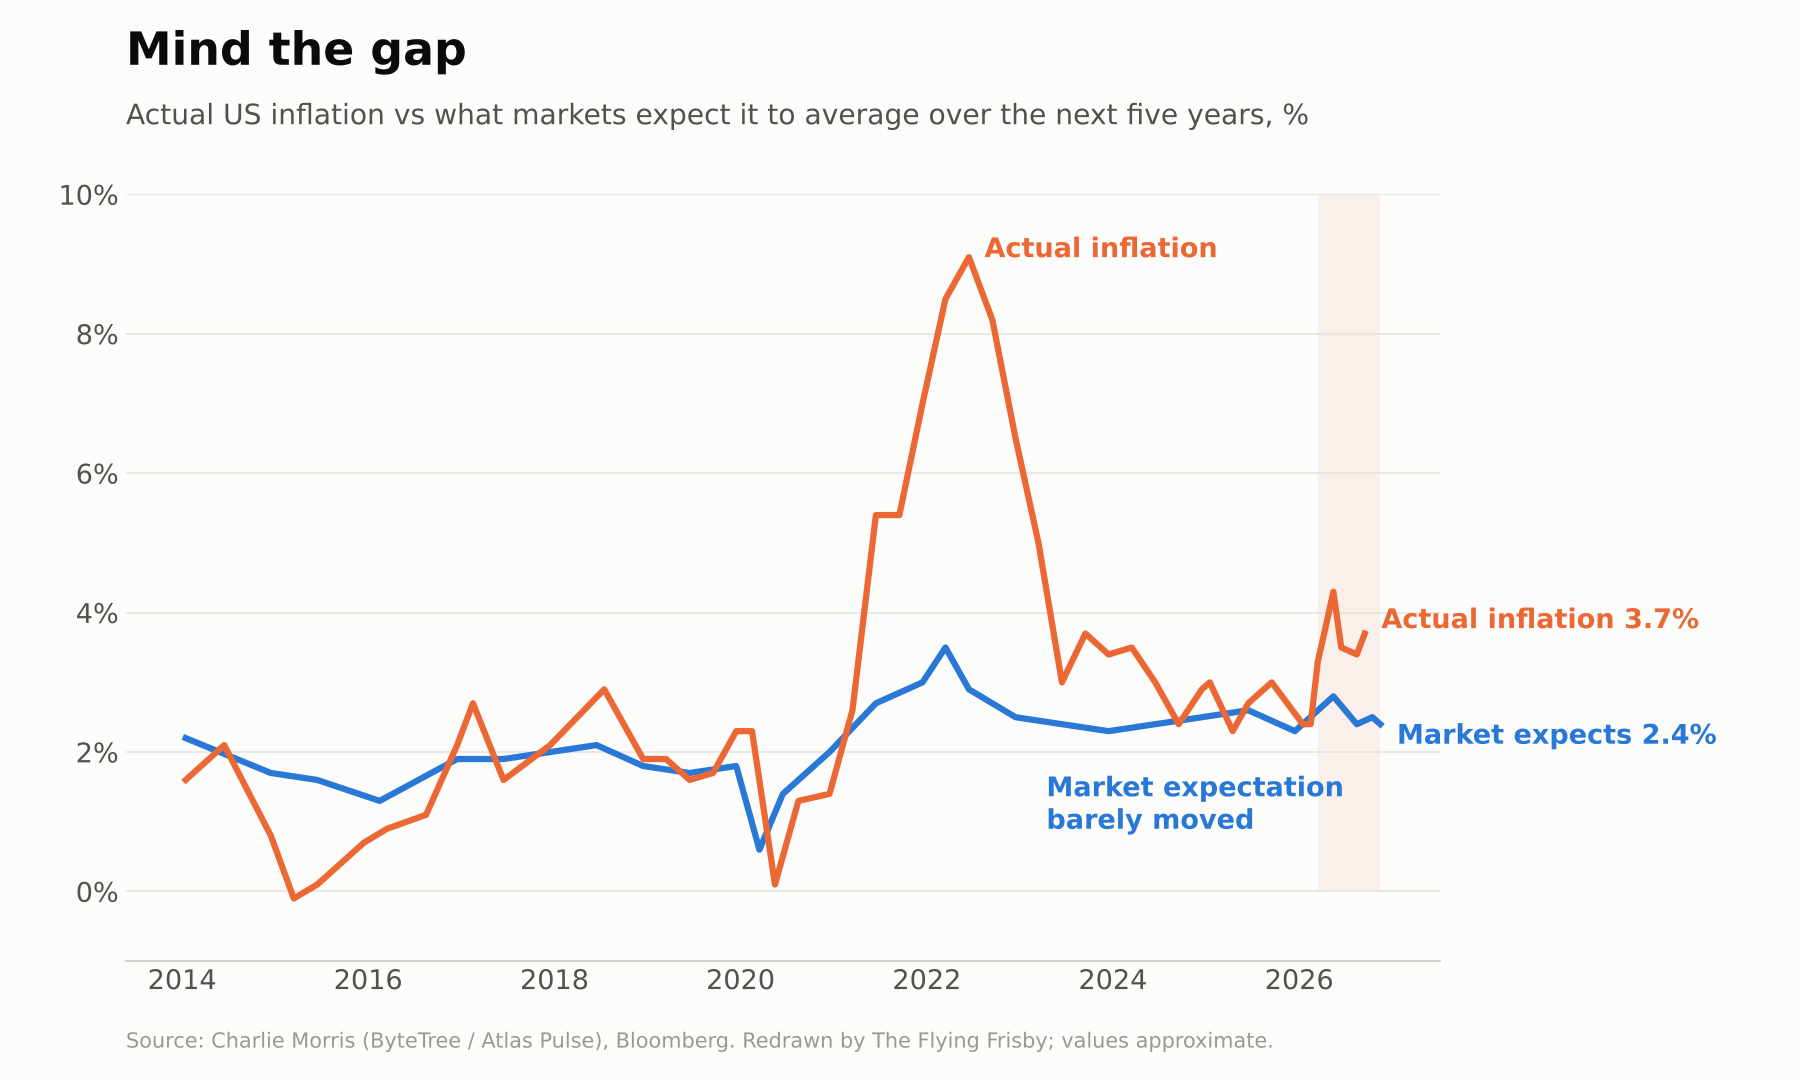
Even in 2022, with inflation at 9%, long-term expectations barely moved. The market seems to have decided, as an article of faith, that inflation will always come back to 2-3%. Either that, or somebody’s putting a lid on the number somehow..
The market is not hedging either. The volatility of long-term inflation expectations is near record lows. Nobody is worried. That level of calm has preceded trouble before, in 2007 and again in 2018.


